Blog · 5 min read
Zero-Based vs. 50/30/20 Budget: Which One Fits You?
A clear comparison of zero-based budgeting and the 50/30/20 rule, with how each works, who it suits, a worked example and how to combine both in one spreadsheet.
Published · SoftPlan Treasures
Two budgeting methods come up again and again: the 50/30/20 rule and the zero-based budget. Both are popular, both work, and they're often presented as rivals. In reality they answer different questions, and many people end up using a bit of each.
Here's how they work, what they're good at, and how to decide which one to start with.
The 50/30/20 rule in one minute
The 50/30/20 rule splits your after-tax income into three buckets:
- 50% for needs: housing, utilities, groceries, insurance, transport to work, minimum debt payments
- 30% for wants: eating out, hobbies, travel, subscriptions, shopping
- 20% for savings and extra debt payments
It was popularised by Elizabeth Warren and Amelia Warren Tyagi in their 2005 book All Your Worth (Investopedia: the 50/30/20 budget rule).
Why people like it
- It's fast. You need one number, your take-home pay, to get started.
- It's flexible. Inside each bucket, you decide what to spend on.
- It's a great health check. Even if you budget another way, comparing your spending against 50/30/20 shows quickly whether needs are crowding everything else out.
Where it struggles
- High-cost housing. In many cities, rent alone can take a large share of income, making 50% for all needs unrealistic. The rule then becomes a goal rather than a description.
- It doesn't plan the details. Knowing you have 30% for wants doesn't tell you whether you can afford the concert and the new coat this month.
- "Needs" vs "wants" can be blurry. Is your phone plan a need? The gym? You have to draw your own lines.
Zero-based budgeting in one minute
A zero-based budget gives every unit of income a job, so that income minus everything you've planned equals zero (Investopedia: zero-based budgeting). "Zero" doesn't mean an empty account. It means nothing is left unassigned: savings, a buffer and fun money are all categories too.
You start from scratch each month (or each paycheck): list your income, then assign it line by line to bills, groceries, savings goals, debt payments and spending until nothing is left.
Why people like it
- Total control. Every expense is a conscious decision.
- It finds leaks. When you have to assign money to "subscriptions", you notice the ones you forgot about.
- It's great for goals. Want to pay off a card or save for a trip? Give it a line and watch it grow.
Where it struggles
- It takes time. Building the plan every month and tracking against it is real work.
- It can feel rigid. Life rarely matches a plan to the last krone or dollar, and constant re-shuffling can be tiring.
- It can be overwhelming at first, especially if you've never tracked your spending before.
A worked example
Imagine a take-home pay of 3,000 in your currency.
With 50/30/20, you'd aim for:
- needs: 1,500
- wants: 900
- savings and extra debt: 600
You then spend within those three limits however you like.
With a zero-based budget, you'd assign the same 3,000 line by line, for example:
| Line | Amount |
|---|---|
| Rent | 1,100 |
| Utilities and internet | 150 |
| Groceries | 350 |
| Transport | 120 |
| Insurance | 80 |
| Phone | 30 |
| Debt payment | 250 |
| Emergency fund | 200 |
| Holiday sinking fund | 100 |
| Christmas sinking fund | 50 |
| Eating out | 150 |
| Hobbies | 100 |
| Clothes | 80 |
| Subscriptions | 40 |
| Buffer | 250 |
| Total | 3,000 |
These are illustrative numbers, not recommendations.
Notice that you can check the zero-based plan against 50/30/20: add up the needs, wants and savings lines and see how close you are. That's the key insight.
Which one should you choose?
Start with 50/30/20 if:
- you've never budgeted before and want something simple
- your income and bills are fairly stable
- you mainly want a quick health check, not detailed control
Choose zero-based if:
- you have a specific goal, like paying off debt or saving for a wedding
- money feels tight and every expense matters
- you like detail and don't mind a monthly planning session
Consider a paycheck budget if:
- you're paid weekly or every two weeks
- you find monthly planning hard to stick to
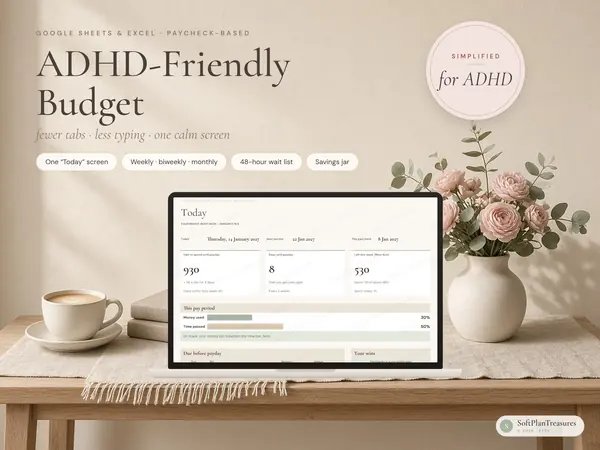
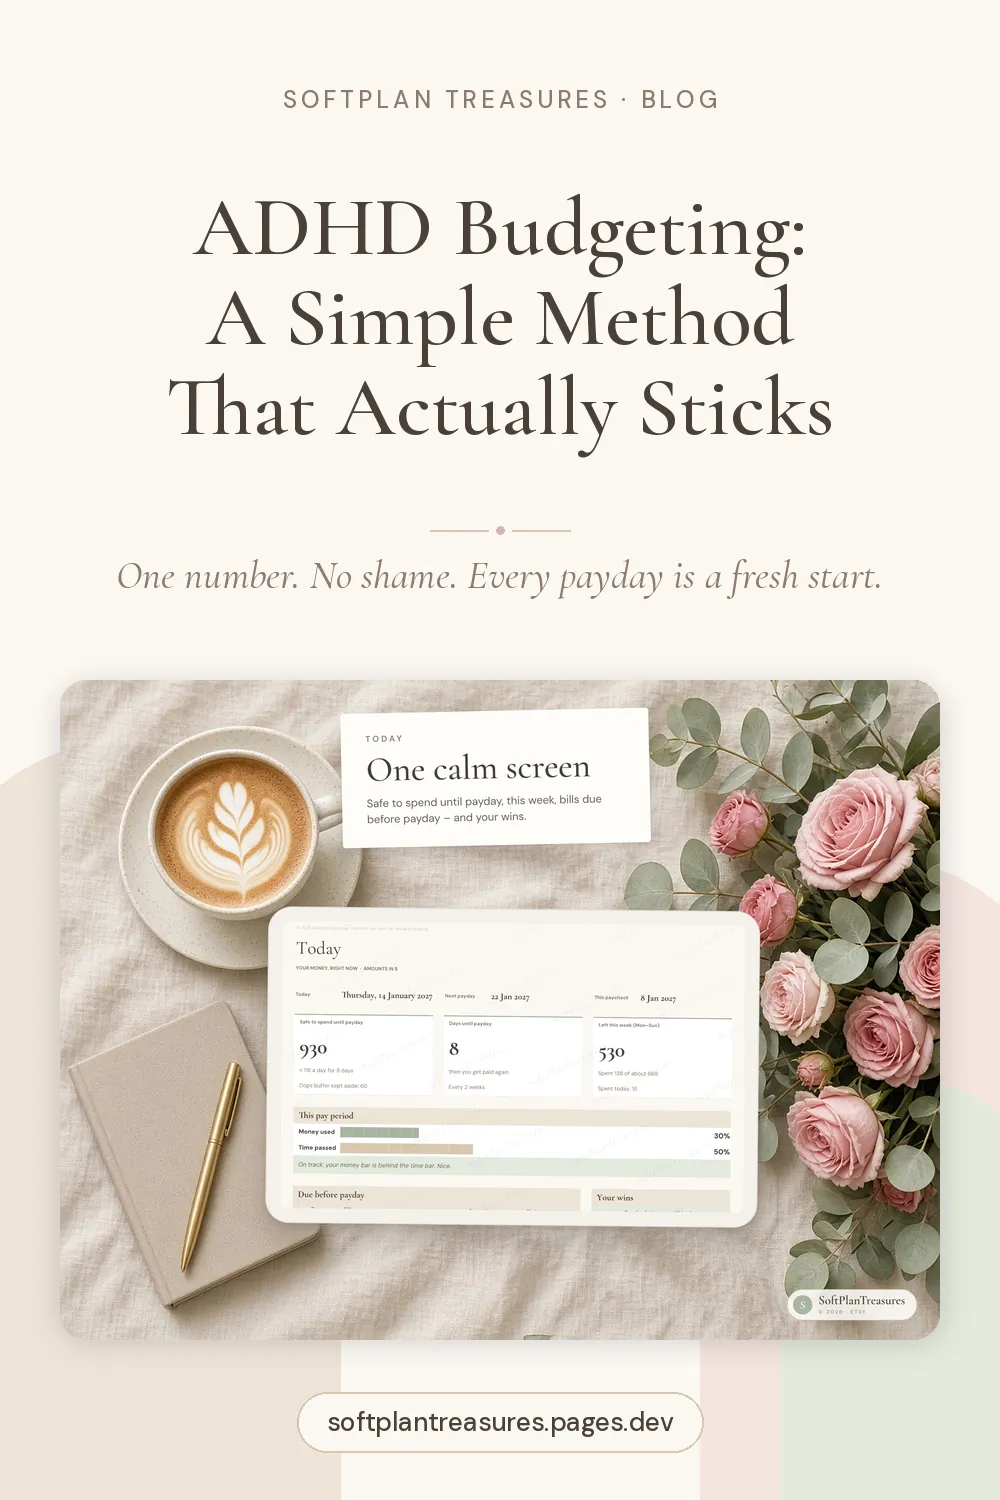
- you have ADHD or simply want fewer numbers to look at. Our post on ADHD budgeting explains this approach
The best of both: plan zero-based, check with 50/30/20
Here's a combination that works well in a spreadsheet:
- Plan each month line by line, so every unit of income has a job.
- Group every line as a need, a want or savings.
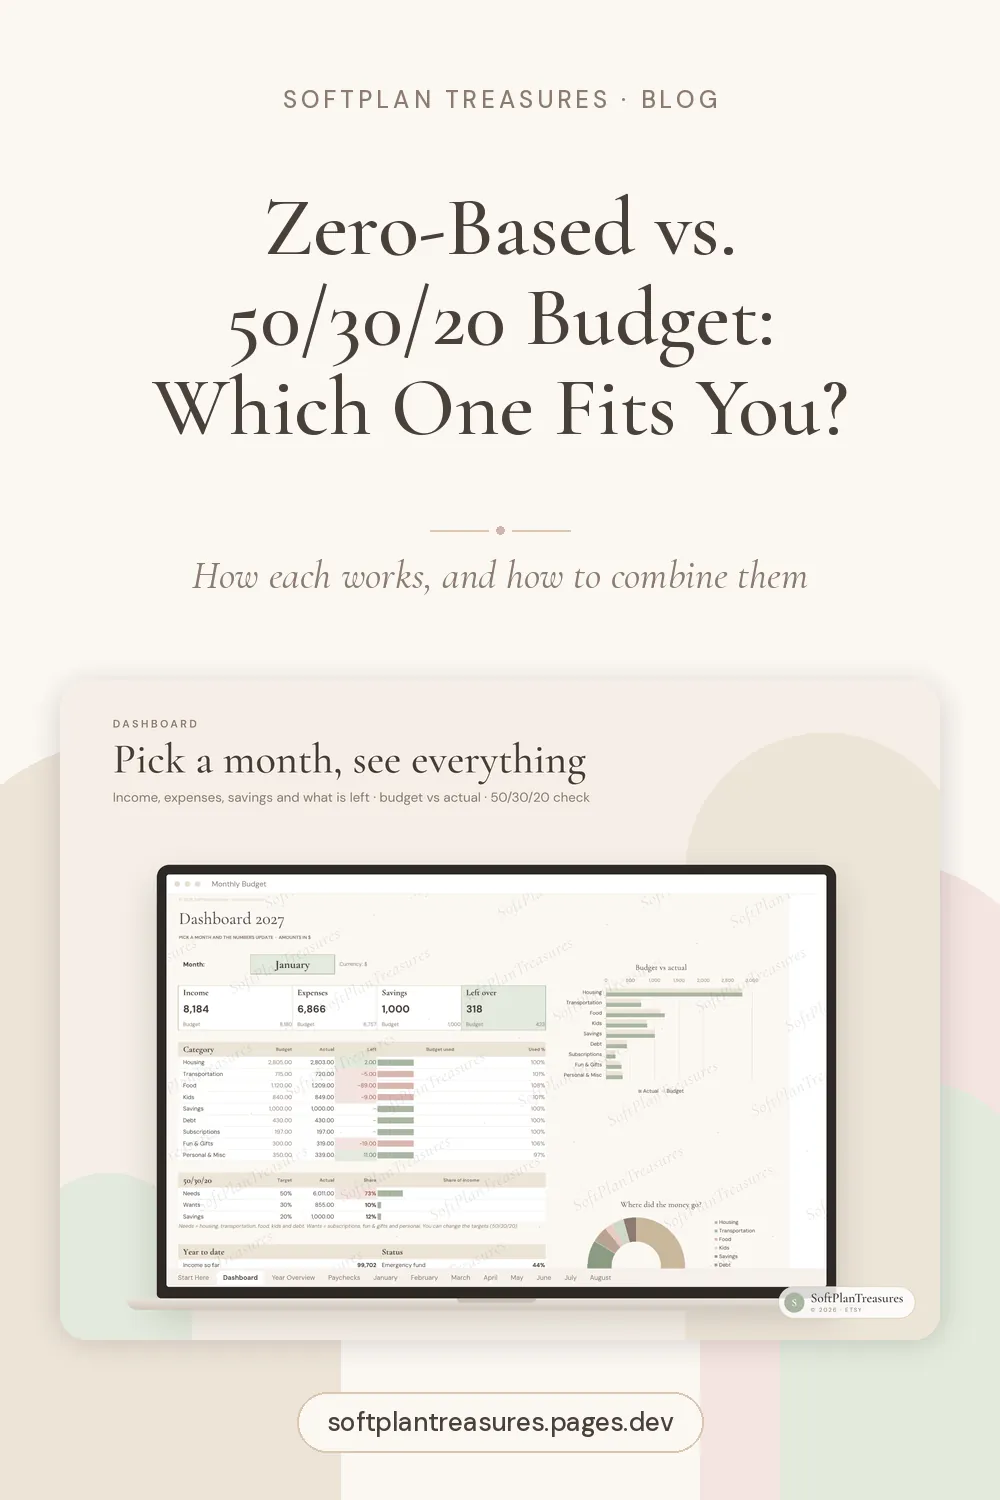
- Check the totals against 50/30/20 on a dashboard.
- Track actual spending next to the plan, and look at the difference.
You get the control of a zero-based budget and the big-picture sanity check of 50/30/20, without doing the maths by hand.
A spreadsheet that does both
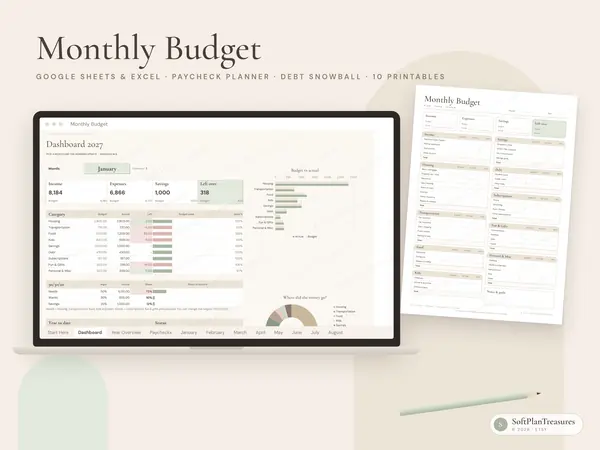
Our monthly budget spreadsheet works exactly like this. You plan a budget for every line in 12 monthly tabs, enter what you actually spent, and the dashboard shows budget versus actual by category, with a built-in 50/30/20 check. It also has a paycheck planner, sinking funds, savings goals with progress bars, debt snowball or avalanche payoff and a net-worth tracker. For Google Sheets and Excel.
Prefer something lighter? The simplified ADHD budget planner shows one "safe to spend until payday" number instead.
Bottom line
50/30/20 tells you whether your spending is balanced. Zero-based tells you exactly where each unit of money goes. You don't have to pick a side. Use the one that gets you to open your budget every week, and borrow from the other when it helps.